When choosing health insurance in the UAE, the premium is only one part of the decision. The hospital network in UAE health insurance can directly affect where you receive treatment, which doctors and specialists you can access, how much you pay yourself, and how convenient healthcare is for you and your family.
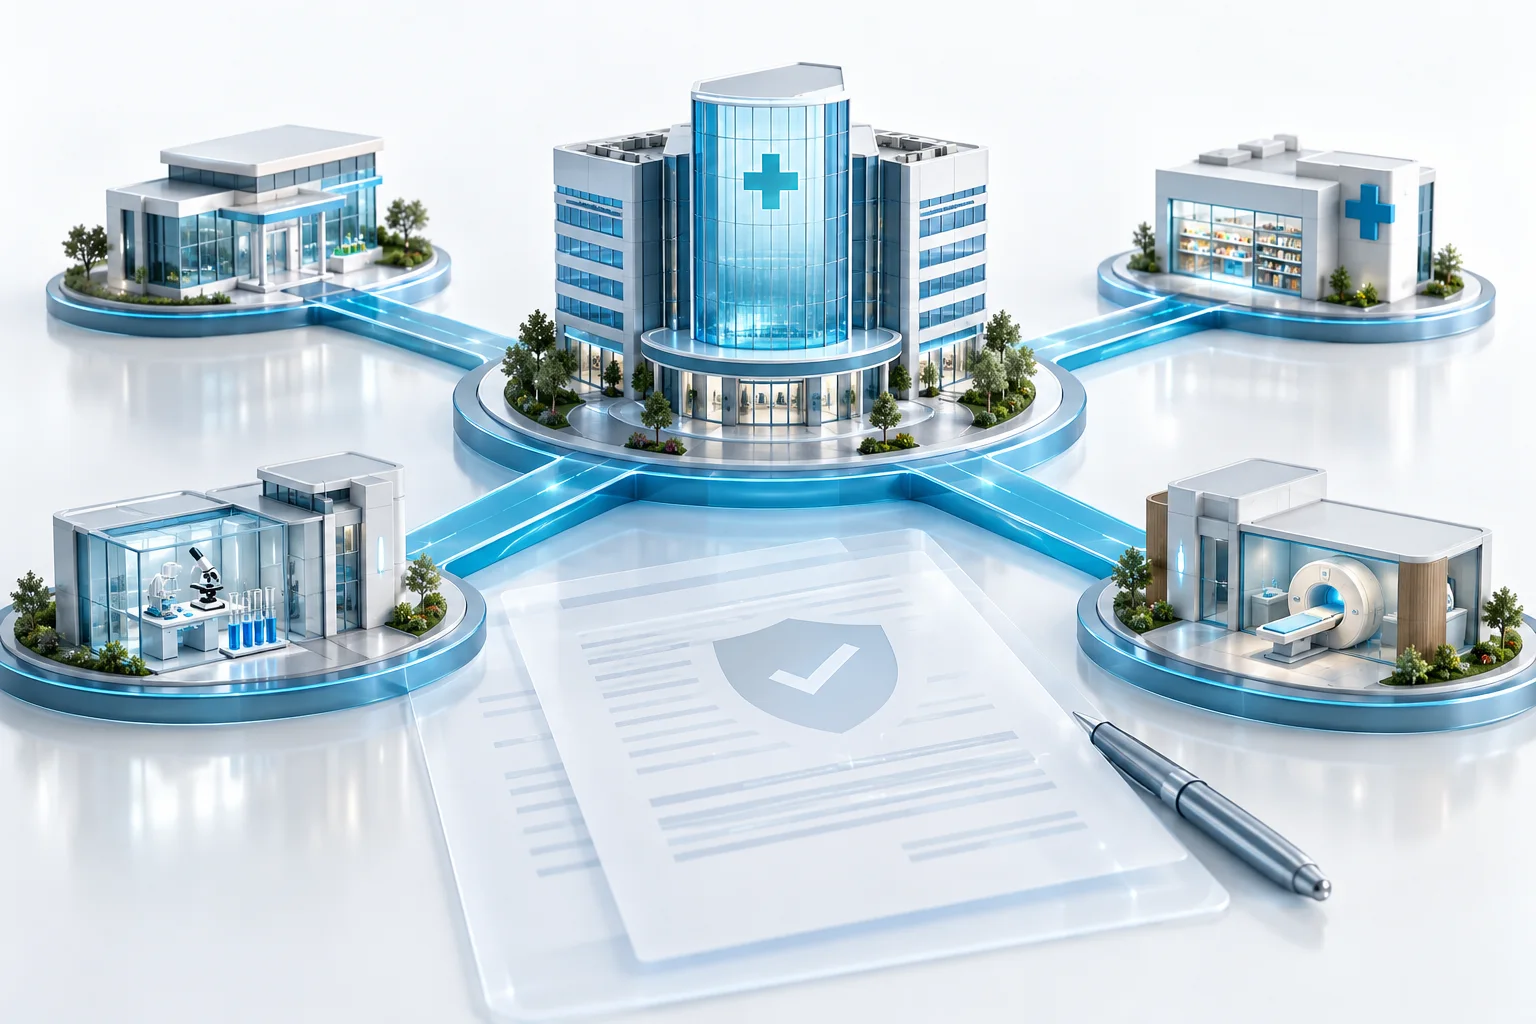
A health insurance network can include hospitals, clinics, pharmacies, laboratories and other healthcare providers. In Dubai, the Health Service Provider Network is defined as the providers listed in the health insurance policy, and insurers are required to provide beneficiaries with and regularly update their provider network.
The important point is that a larger network is not automatically the right network. Your choice should depend on your preferred hospitals, location, healthcare needs, family requirements, budget and the exact terms of the policy.
What Is a Hospital Network in Health Insurance?
A health insurance network is a group or list of healthcare providers that have an arrangement with an insurer or relevant claims or network administrator.
Depending on the policy, the network may include:
- Hospitals
- Clinics
- General practitioners
- Specialists
- Pharmacies
- Laboratories
- Diagnostic centres
- Physiotherapy providers
- Maternity facilities
- Dental or optical providers, where covered
The UAE health insurance network can vary from one policy to another. The same insurer may offer different network tiers, and a hospital that accepts an insurer may not necessarily accept every plan issued by that insurer.
Network participation can also change. Most importantly, being listed in a network does not mean every service provided by that facility is automatically covered. Coverage remains subject to the policy, benefits, exclusions, limits and applicable approval requirements.
Why Does the Hospital Network Matter?
Convenience
A hospital or clinic close to your home, workplace or children's school can make routine consultations, diagnostic appointments and follow-up care easier.
Cost
Using an in-network provider may give you access to the contracted benefits under your policy. Out-of-network treatment may follow different reimbursement rules or may not be covered except where applicable provisions apply.
Your actual cost can also depend on co-payments, deductibles, coinsurance, exclusions and policy limits.
Specialist Access
The number of hospitals is not enough. Consider whether the network includes the specialists and departments you may realistically need.
Family Needs
Families may need convenient access to pediatricians, children's emergency services, maternity facilities, pharmacies and specialist departments.
Continuity of Care
If you already receive ongoing treatment, your existing hospital, specialist, laboratory and pharmacy may be more important than the total number of providers in a network.
Step 1: Start With the Hospitals You Actually Want to Use
Instead of starting with "Which insurance has the biggest network?", start with:
"Which hospitals and healthcare providers do I want access to?"
Make a list of:
- Preferred hospital
- Nearest hospital
- Preferred clinic
- Family doctor
- Pediatrician
- Relevant specialist
- Diagnostic centre
- Pharmacy
- Maternity hospital, where relevant
- Emergency facility
Then check whether each provider is included in the exact network attached to the policy.
Do not rely only on a hospital saying that it "accepts" a particular insurer. A healthcare provider can work with several insurers and different network arrangements.
For example, Dubai Health publishes information about its insurance partners, while individual insurers may maintain their own network directories. This illustrates why the exact insurer, plan and network should be checked rather than relying only on the insurer's name.
Step 2: Check the Exact Network or Plan Tier
Health insurers and TPAs may use different network levels. Names can include Basic, Standard, General, Comprehensive, Gold, Platinum or Executive.
However, these labels do not have a standardized meaning across the UAE.
A "Gold" network from one provider is not necessarily equivalent to a "Gold" network from another.
Compare the actual provider list and policy benefits instead of choosing based on the network name.
Step 3: Check Whether Your Preferred Hospital Accepts Your Exact Plan
This is one of the most important checks before purchasing health insurance.
Confirm:
- Insurer
- TPA or claims/network administrator
- Exact network name
- Exact policy or product
- Hospital branch
- Required service or specialty
A hospital may accept one network while not accepting another network from the same insurer.
For confirmation, check with:
- The insurer
- The TPA or network administrator
- The hospital's insurance desk
Do not rely exclusively on an old provider list, screenshot, broker message or search-engine result.
Current insurer directories can be useful. For example, ADNIC currently provides a searchable medical provider network and distinguishes between its standard and enhanced networks. Its website states that the enhanced network applies to policies effective from 1 August 2026.
Step 4: Check Geographic Coverage
A health insurance network in the UAE should also be evaluated based on geographic coverage.
Consider where you:
- Live
- Work
- Study
- Regularly travel
- Usually seek medical treatment
Think about access across:
- Dubai
- Abu Dhabi
- Sharjah
- Ajman
- Ras Al Khaimah
- Fujairah
- Umm Al Quwain
Do not assume that a Dubai-based policy provides identical access throughout every emirate.
Dubai has its own health insurance framework, while Abu Dhabi operates under its own Department of Health framework. Abu Dhabi's official resources, for example, provide tools for finding healthcare facilities, pharmacies, doctors and registered insurance products.
If you regularly travel between emirates, geographic coverage deserves particular attention.
Step 5: Check Direct Billing and Reimbursement Rules
What Is Direct Billing?
With direct billing, the healthcare provider submits eligible costs to the insurer or relevant claims administrator according to the applicable arrangement and policy terms.
What Is Reimbursement?
With reimbursement, you may pay the healthcare provider first and then submit eligible expenses to the insurer for reimbursement, subject to policy conditions.
Direct billing does not mean zero payment.
You may still have:
- Co-payment
- Deductible
- Coinsurance
- Non-covered services
- Policy limits
- Sub-limits
Before buying, ask:
- Is this hospital available on direct billing?
- Which services are directly billed?
- Are outpatient consultations directly billed?
- Are diagnostics directly billed?
- Are pharmacy services directly billed?
- Is pre-authorization required?
- What patient contribution applies?
Step 6: Look Beyond Hospitals
A healthcare provider network is not simply a hospital list.
Check whether the relevant network includes the providers you are likely to use, such as:
- Clinics
- Specialists
- General practitioners
- Pharmacies
- Laboratories
- Diagnostic centres
- Physiotherapy providers
- Maternity facilities
- Dental providers, if covered
- Mental health providers, if covered
The exact categories and benefits depend on the policy.
Step 7: Match the Network to Your Healthcare Needs
Families With Children
Consider pediatric departments, children's emergency services, pediatric specialists, convenient clinics and nearby pharmacies.
People Managing Chronic Conditions
Look at your existing specialist, relevant hospital department, diagnostic facilities, medication access and follow-up services.
Maternity Planning
Check maternity hospitals, obstetricians, antenatal services, delivery facilities, maternity limits, waiting periods and applicable co-payments.
Do not assume maternity treatment is automatically covered.
Older Adults
Consider specialist availability, chronic disease management, diagnostic services, accessibility, emergency care and geographic convenience.
Frequent Travellers
Check UAE-wide provider access, emergency provisions, geographic limitations and any international medical coverage or assistance included in the policy.
A UAE hospital network should not be confused with international medical coverage.
Step 8: Check Emergency Care Rules
Emergency treatment can be subject to special provisions.
Under Dubai's health insurance law, insurers must pay for covered health benefits provided by a provider outside the network in an emergency until the beneficiary's life is no longer threatened. The implementing framework also addresses emergency treatment at non-network facilities and subsequent transfer considerations.
This should not be interpreted as meaning you can always use any hospital for any treatment without considering your policy.
Emergency provisions, covered services, transfer requirements and subsequent treatment can depend on the applicable law and policy. For non-emergency treatment, network rules remain important.
Step 9: Check Whether the Network Can Change
Healthcare networks are not necessarily permanent.
Providers can:
- Join a network
- Leave a network
- Change contractual arrangements
- Become excluded for particular plans
- Move between network arrangements
Dubai's health insurance framework requires insurers to provide and regularly update provider networks.
Current insurer information also demonstrates why this matters. ADNIC, for example, currently identifies an enhanced network applicable to policies effective from August 2026 and provides a searchable provider directory.
A practical approach is to verify your network:
Before purchasing + before major treatment + at renewal.
Does a Bigger Hospital Network Mean Better Health Insurance?
Not necessarily.
A large network can be useful if you travel frequently or want a wider choice of healthcare providers. A smaller network may still meet the needs of someone who mainly uses healthcare providers in a particular area.
When comparing a health insurance provider network in the UAE, consider:
Common Mistakes When Choosing a Hospital Network
Avoid these mistakes:
- Choosing based only on premium
- Choosing based only on the number of hospitals
- Assuming the insurer's name guarantees access to every hospital
- Ignoring the exact network tier
- Using an outdated provider list
- Not asking about direct billing
- Ignoring co-payments and deductibles
- Ignoring geographic coverage
- Forgetting pharmacies and diagnostic centres
- Not checking specialist availability
- Assuming emergency provisions apply to routine treatment
- Assuming maternity or dental benefits are included
- Not checking network changes at renewal
Hospital Network Checklist Before Buying Health Insurance
Before purchasing, check:
- Identify your preferred hospital
- Check your nearest hospital
- Check nearby clinics
- Check pharmacies
- Check relevant specialists
- Confirm the exact network name
- Confirm the insurer and TPA
- Verify that your hospital accepts your exact plan
- Check direct billing
- Check co-payment and deductible
- Check out-of-network rules
- Check emergency provisions
- Check UAE geographic coverage
- Check maternity benefits if relevant
- Check chronic or pre-existing condition terms if relevant
- Check the current provider list
- Recheck the network at renewal
How to Verify a Hospital Network Before Buying
Follow these steps:
Step 1: Ask the insurer or broker for the exact network provider list.
Step 2: Search for your preferred hospital or clinic by name.
Step 3: Confirm the exact network tier.
Step 4: Contact the healthcare provider's insurance desk.
Step 5: Provide the insurer, TPA, network name and policy/product details.
Step 6: Ask whether your planned service is covered under direct billing.
Step 7: Review the policy wording and Table of Benefits.
Step 8: Save the current network list and policy documents.
Always use current information, particularly before planned treatment.
FAQs About Hospital Networks in UAE Health Insurance
Hospital Network in UAE Health Insurance: How to Make the Right Choice
Choosing a hospital network in UAE health insurance should start with your actual healthcare needs, not simply the number of hospitals listed or the lowest premium.
Start with your preferred providers, check the exact network, verify direct billing, compare geographic access, review specialists and pharmacies, understand co-payments and out-of-network rules, and confirm the latest provider information before treatment.
The right network is the one that fits your healthcare requirements, location, budget and policy terms.
Looking for Health Insurance With the Right Hospital Network?
Insure Now can help you compare health insurance options based on hospital network, coverage, benefits, cost and policy terms.
Before choosing a policy, review the exact provider network and confirm important healthcare access details with the insurer, TPA or healthcare provider.
Related Health Insurance Guides
Explore related health insurance guides, provider access information, and coverage resources for UAE residents.
Articles
- What Is a TPA in Health Insurance UAE?
- Health Insurance Pre-Authorization UAE
- Best Family Medical Insurance Plans in UAE
