Having an insurance claim rejected in the UAE can be frustrating, especially when you believe the loss should be covered. However, a rejected claim does not necessarily mean that you have no further options.
The first step is to understand exactly why the insurer rejected the claim. You should then review the relevant policy wording, gather supporting evidence, and raise the matter with the insurance company through its formal complaint process.
If the complaint is not resolved and you meet the applicable eligibility requirements, you may be able to escalate the matter to Sanadak, the UAE's financial and insurance ombudsman.
The outcome of any dispute depends on the policy terms, evidence, circumstances of the claim, and applicable UAE laws and regulations. Challenging a rejection does not guarantee that the claim will ultimately be paid.
Why Do Insurance Companies Reject Claims in the UAE?
Insurance claims can be rejected for different reasons. Whether a rejection is justified depends on the specific policy, the circumstances of the claim, and the evidence available.
Common reasons may include:
- The event is excluded under the policy.
- The loss is outside the scope of the coverage.
- A required policy condition was not met.
- The policy was not active when the incident occurred.
- Required claim procedures were not followed.
- Required documents or information were not provided.
- The claimed loss could not be sufficiently established.
- The information provided was incomplete or inconsistent.
- The insurer identified possible misrepresentation, non-disclosure, or fraud.
- The circumstances of the incident do not meet the applicable policy requirements.
None of these reasons automatically means that the insurer's decision is correct or incorrect. The rejection should be assessed against the actual policy wording and the evidence relating to the claim.
Ask for the rejection reason in writing
If your claim has been rejected, ask the insurer to provide the decision and reasons in writing.
For an insurance claim that has been rejected wholly or partly, the insurer should state the reasons for the rejection in accordance with the applicable UAE insurance framework.
A written explanation can help you determine:
- Why the claim was rejected
- Which policy clause, exclusion, or condition the insurer relied upon
- What evidence was considered
- Whether additional information is required
- Whether there is a basis for asking the insurer to reconsider the decision
Some information may be subject to legal or confidentiality restrictions, so an insurer may not necessarily be able to provide every document or internal record requested.
8 Steps to Challenge an Insurance Claim Rejection in the UAE
Step 1: Get the Rejection Reason in Writing
Start by obtaining a clear written explanation from the insurance company.
Ask the insurer to identify:
- The specific reason for the rejection
- The relevant policy clause, exclusion, or condition
- The information or evidence relied upon
- Any missing information that could affect the assessment
- The process for requesting reconsideration or submitting a complaint
Keep the rejection letter, email, portal notification, or other written communication.
A written decision gives you something concrete to compare against your policy and supporting evidence.
Step 2: Review Your Insurance Policy Carefully
Do not rely only on the insurance certificate or a short policy summary. Review the complete policy documentation available to you.
Pay particular attention to:
- Policy schedule
- Policy wording
- Covered benefits
- Exclusions
- Conditions
- Deductibles or excesses
- Endorsements
- Special terms
- Coverage limits
- Geographical restrictions
- Usage restrictions
The key question is:
What specific provision of the policy is the insurer relying on to reject the claim?
Compare that provision with what actually happened.
For example, if the insurer says that a particular loss is excluded, read the complete exclusion together with any definitions, exceptions, conditions, or related provisions. The wording surrounding an exclusion can be just as important as the exclusion itself.
Step 3: Check the Evidence Supporting Your Claim
A strong insurance dispute should be supported by relevant evidence rather than assumptions.
Depending on the type of insurance and the circumstances of the claim, useful documents may include:
- Police or accident reports
- Medical records
- Hospital documents
- Photographs and videos
- Repair estimates
- Repair invoices
- Receipts
- Proof of ownership
- Travel documents
- Property damage evidence
- Claim forms
- Emails and correspondence with the insurer
- Expert reports, where relevant
Organize your documents chronologically and keep copies of everything you submit.
Evidence requirements differ between motor, health, property, travel, life, and other insurance products. Only provide documents that are relevant to your particular claim.
Step 4: Submit a Formal Complaint to the Insurer
Before escalating the dispute externally, use the insurance company's formal complaint process.
Your complaint should clearly explain the issue and identify the outcome you are requesting.
Include, where applicable:
- Policy number
- Claim number
- Date of the incident
- Date the claim was submitted
- Date of the rejection
- Reason given for the rejection
- Relevant policy provision
- Why you disagree with the decision
- Supporting evidence
- The resolution you are requesting
Keep proof that your complaint was submitted. This could include an email, complaint reference number, portal confirmation, or written acknowledgment from the insurer.
Avoid making unsupported accusations. Instead, explain the factual issue, identify the relevant policy wording, and show why you believe the evidence supports reconsideration.
Step 5: Check Whether You Are Eligible to Escalate to Sanadak
If the insurer does not resolve your complaint satisfactorily, you may be able to escalate an eligible complaint to Sanadak.
Sanadak provides an independent complaint-resolution route for eligible complaints involving financial institutions and insurance companies that fall within its regulatory scope.
For an insurance complaint, you generally need to:
- Submit an official complaint to the insurance company first.
- Allow 15 calendar days to pass.
- Have either received no written response or received a response that you are not satisfied with.
- Meet Sanadak's other applicable eligibility requirements.
The 15-day period should not be treated as the only eligibility requirement. Sanadak may decline complaints that fall outside its jurisdiction or otherwise fail to satisfy its eligibility criteria.
Sanadak can deal with eligible complaints relating to areas such as:
- Motor insurance
- Health insurance
- Property insurance
- General insurance
- Marine insurance
- Life insurance
- Other insurance matters within its regulatory scope
Sanadak is not a guarantee that an insurer's decision will be overturned. An eligible complaint is independently reviewed and may be upheld, partially upheld, or rejected.
Step 6: Prepare Strong Evidence for Sanadak
If you are eligible to submit a complaint to Sanadak, prepare a complete case file.
Depending on the dispute, this may include:
- Insurance policy
- Policy schedule
- Claim number
- Rejection letter
- Correspondence with the insurer
- Your formal complaint to the insurer
- Insurer's response
- Police reports, where applicable
- Medical documents
- Repair documents
- Photographs and videos
- Invoices and receipts
- Relevant expert reports
- A chronological summary of events
Keep your explanation factual and focused.
Instead of simply saying that the insurer "unfairly refused to pay," explain:
- What happened
- What you claimed
- What the insurer decided
- Why the insurer rejected the claim
- Which policy provision was relied upon
- What evidence you provided
- Why you believe the decision should be reconsidered
- What resolution you are requesting
Sanadak may request additional information during its review.
Step 7: Understand the Sanadak Decision and Appeal Process
Sanadak reviews eligible complaints and communicates its determination in accordance with its applicable procedures.
The outcome may be favorable to the complainant, partially favorable, or unfavorable.
If you are dissatisfied with an eligible insurance complaint determination, an appeal may be available through the Insurance Dispute Resolution Committee, subject to the applicable requirements.
Sanadak currently states that an appeal carries a fee of AED 500 per appeal, with the fee refundable where the determination is in the appellant's favor. Because fees and procedural requirements can change, check the current Sanadak instructions when submitting an appeal.
Do not assume that every Sanadak determination can automatically be appealed. Check the applicable eligibility and procedural requirements for your case.
Step 8: Consider Professional Legal Advice
If the dispute remains unresolved, consider obtaining advice from a qualified UAE legal professional.
Legal advice may be particularly useful where:
- The dispute involves a significant amount of money.
- The policy wording is complex.
- There is a serious disagreement about liability or coverage.
- The insurer alleges fraud or misrepresentation.
- The matter involves complicated contractual or regulatory issues.
- You are considering court proceedings.
- You are unsure about your rights or the appropriate dispute-resolution route.
The appropriate next step can depend on the type of insurance, policy terms, value of the dispute, applicable regulations, Sanadak eligibility, and whether another legal or dispute-resolution process is already underway.
Before starting court proceedings, understand the applicable dispute-resolution requirements and whether the matter is eligible for or required to go through the relevant complaint process.
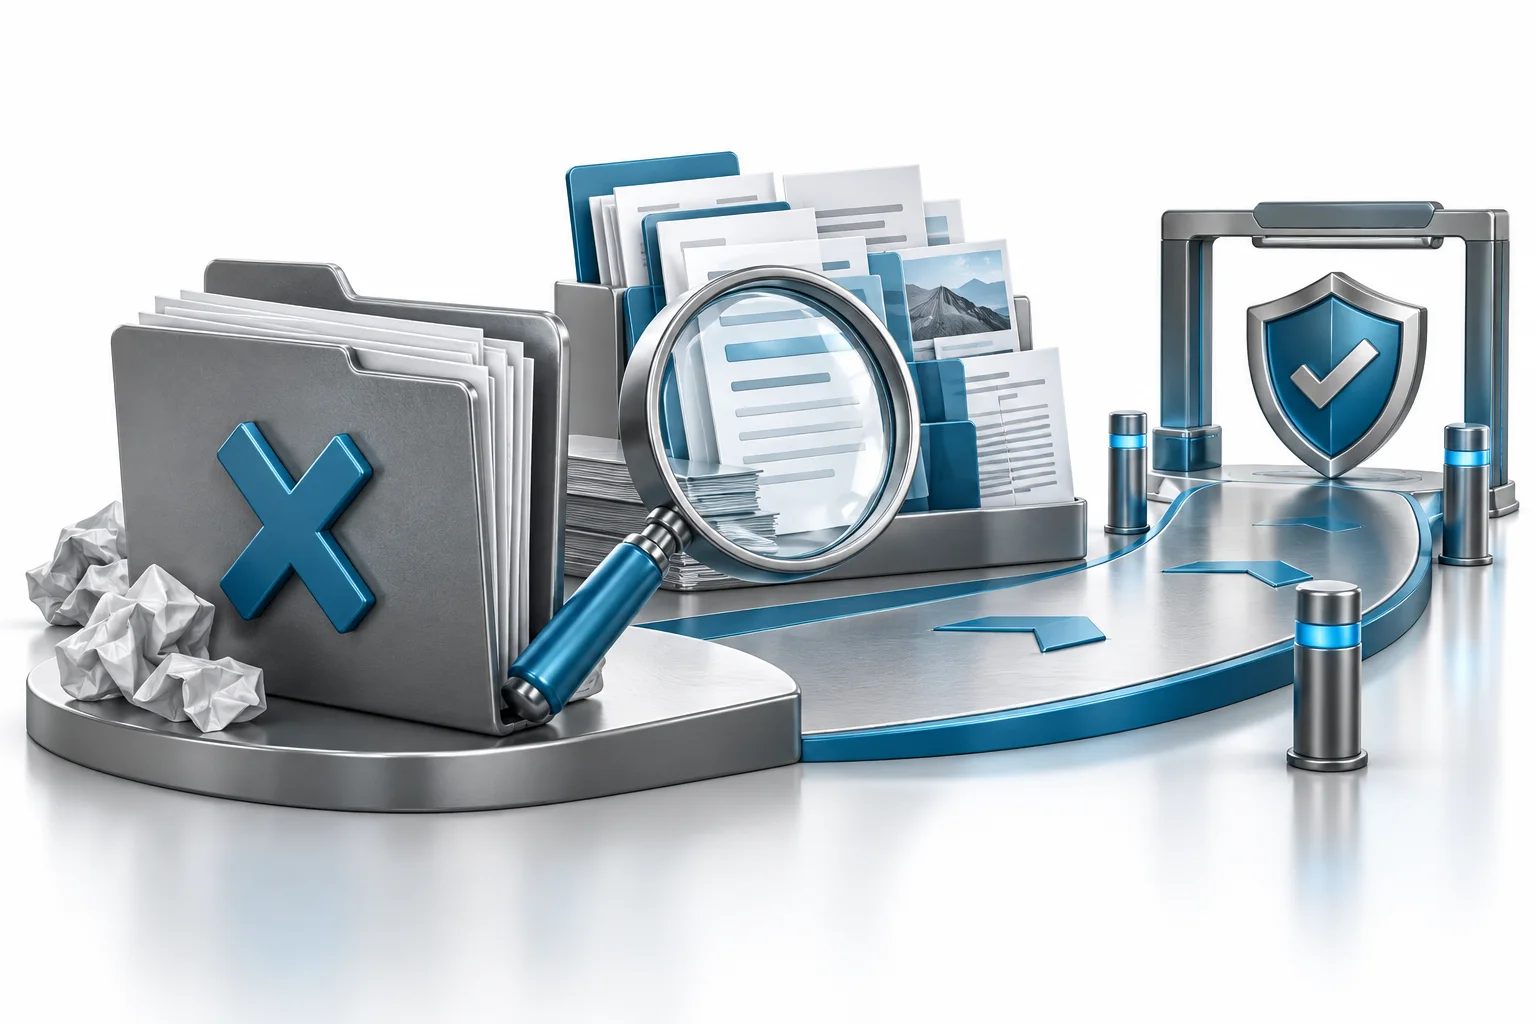
Insurance Claim Rejection: What Is the Escalation Path?
This is a practical framework, not a guarantee that every insurance dispute will follow exactly the same sequence.
Common Mistakes After an Insurance Claim Is Rejected
Avoid these common mistakes:
- Accepting a verbal rejection without asking for written reasons
- Ignoring the full policy wording
- Failing to identify the specific exclusion or condition relied upon
- Submitting incomplete evidence
- Missing applicable deadlines or procedural requirements
- Making unsupported accusations against the insurer
- Providing contradictory information
- Destroying, altering, or losing evidence
- Signing a settlement without understanding its effect
- Escalating before completing the insurer's complaint process
- Assuming that every rejected claim means the insurer violated UAE law
- Assuming that Sanadak will automatically overturn the insurer's decision
A calm, documented approach is generally more effective than an emotional argument.
Insurance Claim Rejection Checklist
Before escalating an insurance dispute, check that you have:
- Obtained the rejection in writing
- Identified the exact rejection reason
- Found the relevant policy clause
- Reviewed exclusions and conditions
- Gathered supporting documents
- Prepared a timeline of events
- Submitted a formal complaint to the insurer
- Kept proof of your complaint submission
- Allowed the applicable response period to pass
- Checked your eligibility for Sanadak
- Prepared the relevant evidence for Sanadak, if eligible
- Reviewed the Sanadak determination carefully
- Considered an appeal or professional legal advice where appropriate
Does the Process Differ for Car, Health and Other Insurance Claims?
The general complaint process can be similar, but the evidence and policy terms can differ significantly depending on the type of insurance.
Car Insurance
A rejected motor insurance claim may involve:
- Accident report
- Police report
- Vehicle inspection
- Accident photographs
- Repair estimate
- Repair invoices
- Policy wording
- Vehicle documents
- Correspondence with the insurer
Health Insurance
A rejected health insurance claim may involve:
- Medical reports
- Diagnosis
- Treatment records
- Prescriptions
- Pre-authorization correspondence
- Benefit schedule
- Medical invoices
- Written explanation for the rejection
Property Insurance
Useful evidence may include:
- Damage photographs
- Police or fire reports, where applicable
- Repair estimates
- Ownership or tenancy documents
- Receipts
- Loss assessment reports
- Correspondence with the insurer
Travel Insurance
Possible evidence includes:
- Airline documents
- Cancellation confirmation
- Medical documents, where relevant
- Receipts
- Travel itinerary
- Proof of delay or disruption
These are examples only. The actual evidence required depends on the policy, insurer, type of claim, and circumstances of the loss.
Frequently Asked Questions About a Rejected Insurance Claim in the UAE
Insurance Claim Rejected in the UAE: What Should You Do Next?
If your insurance claim is rejected in the UAE, do not assume that the decision is automatically final. At the same time, do not assume that the rejection is automatically wrong.
A practical approach is:
Understand the rejection → review the policy → collect evidence → complain to the insurer → check Sanadak eligibility → escalate if appropriate → consider an appeal or legal advice where applicable.
The strongest insurance dispute submissions are usually based on clear documentation, relevant policy wording, and a factual explanation of why the decision should be reconsidered.
A complaint or appeal does not guarantee compensation. Whether a claim is payable depends on the policy terms, applicable UAE laws and regulations, evidence, and circumstances of the claim.
Need Help Understanding Your Insurance Options in the UAE?
Understanding your insurance coverage before a claim arises can make future decisions easier to navigate.
Insure Now provides information to help UAE consumers understand insurance options and make more informed decisions. Review your policy carefully, understand its exclusions and conditions, and compare your available options before making an insurance decision.
Related Insurance Claim Guides
Explore practical guides about insurance claims, coverage, and dispute resolution in the UAE.
Articles
- Common Reasons Insurance Claims Get Rejected in the UAE
- How Insurance Claims Work in the UAE
- Contact Insure Now About Claims
