Building Insurance vs Contents Insurance UAE: Key Differences
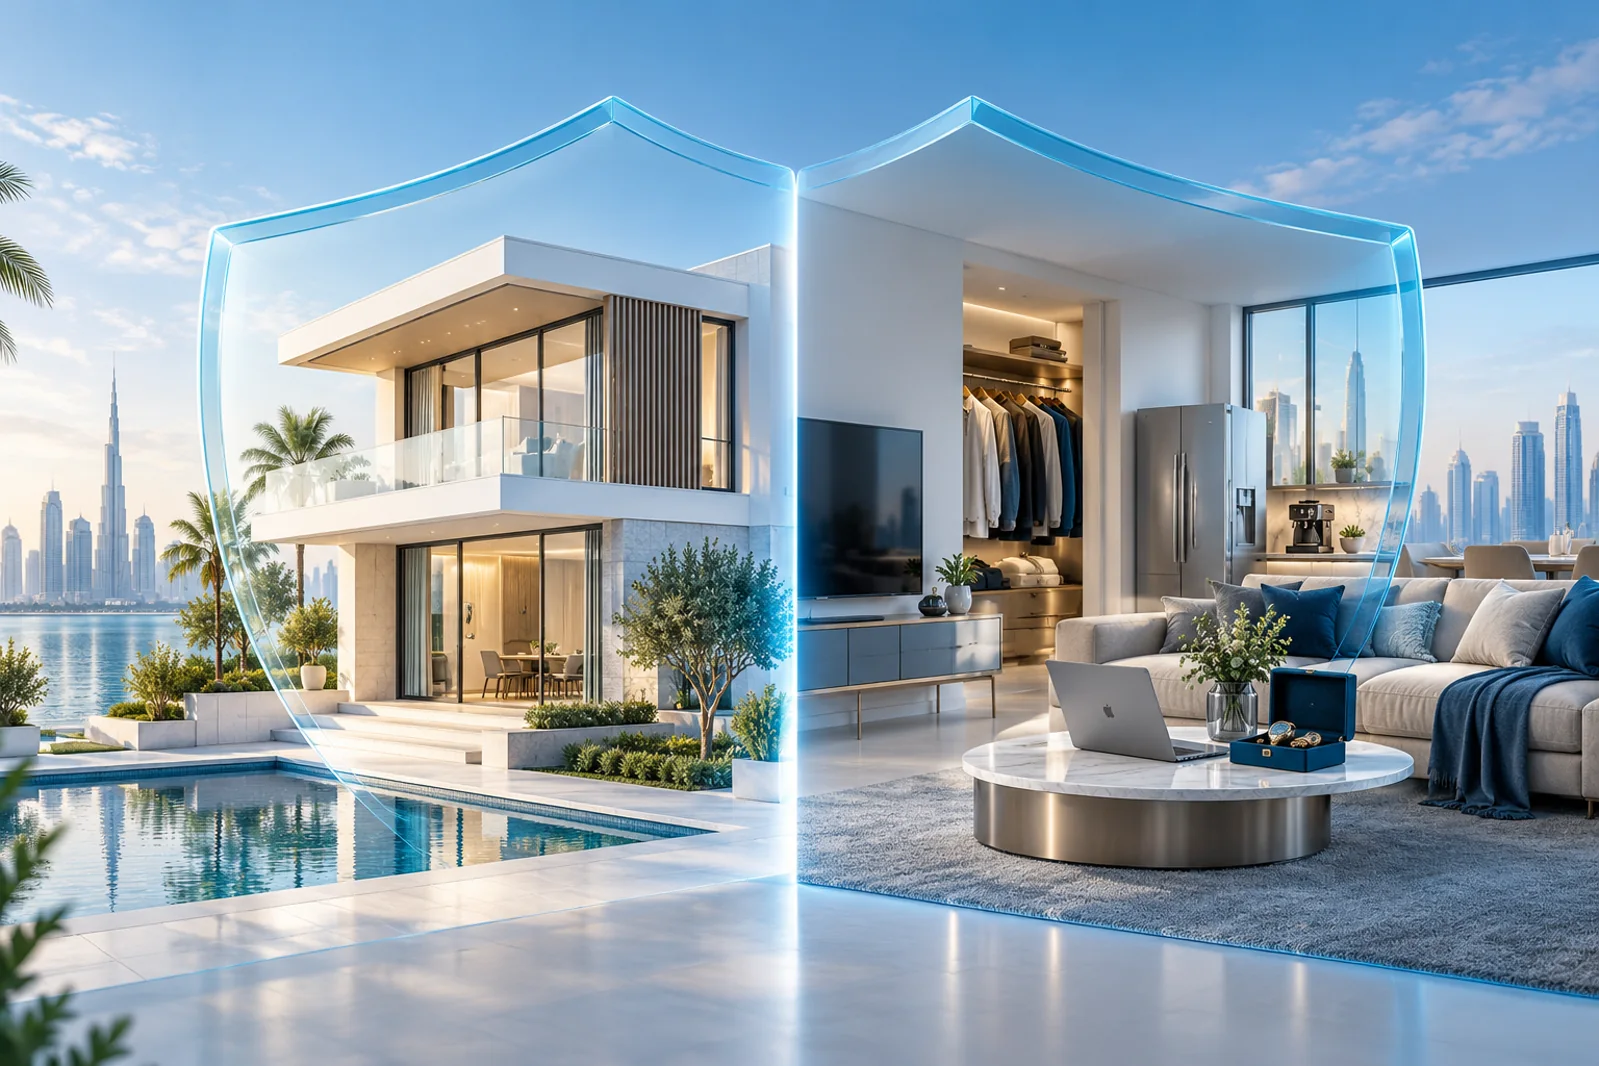
Imagine you own a villa in Dubai. The property itself includes walls, floors, doors, windows and other fixed elements. Inside, you have a sofa, television, laptop, clothing, kitchen equipment and other possessions.
These represent different types of insurance risk.
Building insurance generally protects the eligible physical structure of the property, while contents insurance generally protects eligible household belongings kept inside it, subject to the policy terms. Personal belongings and valuables may be treated separately by some insurers.
This distinction matters because having one type of cover does not automatically mean the other is insured. Current UAE products demonstrate different approaches. For example, current UAE products offer buildings-only, buildings-and-contents, and contents-only arrangements depending on ownership and occupancy. Some insurers also allow customers to select building, contents, or contents and building cover, while separately identifying personal belongings.
So, when comparing building insurance vs contents insurance UAE, the first step is to understand what each section is designed to protect.
What Is Building Insurance in the UAE?
Building insurance, sometimes called structure insurance, generally protects the physical structure of an insured residential property against specified insured events, subject to the policy wording.
Depending on the insurer and policy, the building or structure may include:
- Walls
- Roof
- Floors
- Ceilings
- Doors
- Windows
- Fixed structural elements
- Certain fixed fixtures and fittings
- Other permanent structures specified in the policy
However, you should not assume every fixture automatically qualifies as building cover. The treatment of fitted kitchens, wardrobes, air-conditioning equipment, sanitary fixtures and other fixed items can depend on the policy definition and ownership arrangement.
The policy wording and schedule should therefore take priority over the general label "building insurance."
What Is Contents Insurance in the UAE?
Contents insurance generally protects eligible household possessions kept within the insured home against the insured events stated in the policy.
Examples can include:
- Furniture
- Television
- Computers
- Household appliances
- Clothing
- Kitchenware
- Crockery
- Sports equipment
- Home furnishings
- Other eligible household goods
This is an important reminder that contents insurance UAE does not have one universal definition across all insurers.
Building Insurance vs Contents Insurance UAE: What Is the Difference?
| Feature | Building Insurance | Contents Insurance |
|---|---|---|
| Main purpose | Protects the eligible property structure | Protects eligible household belongings |
| Walls | Generally relevant | No |
| Roof | Generally relevant | No |
| Floors | Generally relevant | No |
| Fixed elements | Policy-dependent | Policy-dependent |
| Furniture | Generally not building cover | Generally relevant |
| Television | Generally not building cover | Generally relevant |
| Clothing | No | Generally relevant |
| Appliances | Depends on whether fixed or movable | Often relevant for movable appliances |
| Jewellery | Usually not building cover | May require valuables or personal belongings cover |
| Tenant's belongings | No | Yes, if insured |
| Typical users | Owners and landlords | Owners and tenants |
| Valuation | Policy-specific building/reinstatement basis | Policy-specific contents valuation basis |
Exact classifications depend on the insurer and policy wording. The table is a practical guide, not a universal legal definition.
Do Homeowners Need Building and Contents Insurance?
An owner-occupier may need to consider both building and contents because they can have separate financial interests in the structure and the belongings inside it.
For example, a villa owner may have building-related exposure involving the walls, roof, floors and other eligible fixed structures. At the same time, the household may own furniture, televisions, clothing, computers and other possessions that could fall under contents or personal belongings.
This does not mean every homeowner is legally required to purchase both. The appropriate combination depends on the property arrangement, ownership, applicable requirements and the insurer's policy.
Do Tenants Need Building Insurance in the UAE?
A tenant generally does not insure the building structure they do not own.
Instead, a tenant may consider cover for their own:
- Furniture
- Electronics
- Clothing
- Personal belongings
- Other eligible possessions
- Tenant liability, where available
- Alternative accommodation, where available
What If You Own a Property and Rent It Out?
Landlords have different insurance considerations from people who live in their own homes.
A landlord may consider:
- Building or structure cover
- Loss of rent, where available
- Landlord liability, where available
- Other property-related covers
The landlord should not automatically assume that the tenant's furniture, electronics, clothing or personal belongings are insured under the landlord's policy.
What Counts as a Building or Structure?
The exact definition varies, but potential building elements can include:
- Walls
- Roof
- Floors
- Ceilings
- Doors
- Windows
- Fixed sanitary fixtures
- Certain fixed plumbing or electrical installations
- Permanent structures
Built-in kitchens, wardrobes, air-conditioning units and similar installations require particular attention. Their classification can depend on the policy wording, ownership and whether they are considered landlord fixtures or insured property.
Therefore, do not assume that every fitted item automatically belongs under building insurance.
What Counts as Contents?
A practical room-by-room inventory can make it easier to calculate your contents value.
Living Room
- Sofa
- Chairs
- TV
- Sound system
- Rugs
- Lamps
- Furniture
- Decorative items
Bedroom
- Bed
- Mattress
- Wardrobe
- Clothing
- Furniture
- Personal items
Kitchen
- Kitchenware
Cookware
- Small appliances
- Utensils
- Crockery
- Other eligible household goods
Home Office
- Computer
- Monitor
- Printer
- Desk
- Office equipment
Business equipment may be subject to different conditions, so check the policy before assuming it is covered.
Storage Areas
- Tools
- Household equipment
- Suitcases
- Sports equipment
- Stored belongings
What About Jewellery, Watches and Laptops?
High-value and portable items deserve special attention.
Depending on the insurer, they may be classified as:
- Personal belongings
- Valuables
- Portable equipment
- Specified items
Before buying cover, check:
- Single-item limits
- Category limits
- Whether expensive items must be declared
- Whether cover applies outside the home
- Whether valuation documents are required
Do not assume that jewellery or a laptop is automatically covered simply because you have contents insurance.
Building Insurance vs Contents Insurance for Apartments and Villas
Apartment Owner
An apartment owner may need to consider:
- Building or structure responsibilities
- Contents
- Personal belongings
- Liability
Apartment ownership can involve additional considerations because structural responsibilities may involve building management, owners' associations or other arrangements.
Do not assume that any building-level insurance automatically protects your personal belongings.
Villa Owner
A villa owner may consider:
- Building
- Contents
- Personal belongings
- Outdoor items, where covered
- Liability
Tenant
A tenant will generally focus on:
- Contents
- Personal belongings
- Tenant liability, where available
- Other applicable benefits
These are not mandatory combinations for every resident. The policy and circumstances determine the appropriate coverage.
How Much Building Insurance Do You Need?
The building sum insured should be calculated according to the valuation basis required by the insurer and policy.
Do not automatically use:
- Property market value
- Purchase price
- Mortgage amount
- Land value
- Sale price
These figures are not automatically the building insurance value.
Market value is not automatically the same as rebuilding or reinstatement value.
Your insurer may have specific requirements for determining the building sum insured. Follow those instructions rather than applying a generic AED-per-square-foot estimate.
How Much Contents Insurance Do You Need?
Your contents sum insured should reflect the eligible possessions you want to protect and the valuation method specified by the policy.
A practical approach is:
- Walk through every room.
- List major possessions.
- Estimate their replacement value using the policy's valuation basis.
- Identify high-value items.
- Check single-item limits.
- Review personal belongings cover.
- Update your inventory after major purchases.
Also check whether the policy contains an underinsurance or average clause and understand how it could affect a claim.
Look at replacement cost, depreciation, sum insured, single-item limits and category limits rather than assuming every home policy uses the same settlement method.
Can Building and Contents Insurance Be Bought Together?
Yes, some UAE home insurance products offer combined building and contents cover.
However, this does not mean every home insurance policy automatically includes both.
The available combinations, limits, exclusions and eligibility conditions can vary between insurers.
What Other Covers Should Homeowners and Tenants Consider?
Depending on the policy, additional sections may include:
- Personal belongings
- Personal liability
Tenant liability
Alternative accommodation
- Loss of rent
- Home assistance
- Accidental damage
- Domestic helper cover
- Contents temporarily removed
- Important documents
- Money and credit cards
These should not be treated as universal benefits. Always check the policy schedule and wording.
Common Mistakes When Choosing Home Insurance in the UAE
Avoid these common mistakes:
- Assuming building insurance covers furniture.
- Assuming contents insurance covers the physical structure.
- Insuring a building as a tenant when you do not own it.
- Forgetting to insure contents as a homeowner.
- Assuming the landlord's policy covers tenant belongings.
- Ignoring personal belongings cover.
- Using market property value as the building sum insured without checking the policy basis.
- Underestimating the value of household contents.
- Ignoring high-value item limits.
- Not checking liability cover.
- Assuming flood or water damage is automatically covered.
- Buying a policy without reviewing exclusions.
Building vs Contents Insurance Checklist
If You Own and Live in the Property
- Check building cover
- Calculate contents value
- Check personal belongings
- Identify valuables
- Review liability cover
- Check alternative accommodation provisions
- Review exclusions
If You Are a Tenant
- Calculate contents value
- Check personal belongings
- Check tenant liability
- Check alternative accommodation
- Identify valuables
- Check portable electronics cover
If You Are a Landlord
- Check building cover
- Check loss-of-rent provisions
- Review landlord liability
- Confirm occupancy conditions
- Understand tenant responsibilities
- Do not assume tenant belongings are covered
Frequently Asked Questions
Building Insurance vs Contents Insurance UAE: Which Cover Applies to You?
The key difference is straightforward:
Building insurance generally protects the eligible property structure.
Contents insurance generally protects eligible household possessions.
Personal belongings may be classified separately.
Valuables may have separate limits or requirements.
Tenants generally focus on insuring belongings they own.
Owner-occupiers may consider both buildings and contents.
Landlords may focus on the building and landlord-specific covers.
The important point is to look beyond the policy name. Check the actual coverage sections, limits, exclusions, valuation basis, occupancy conditions and definitions before choosing a home insurance policy. Current UAE products show that these details can differ between insurers.
Compare Home Insurance Options in the UAE
Whether you are a tenant, homeowner, owner-occupier or landlord, the appropriate home insurance structure depends on what you own, your occupancy arrangement and the risks you want to cover.
Explore Home Insurance options with Insure Now to compare suitable coverage options for your circumstances and understand the differences between building, contents and related covers. Insure Now provides guidance on home insurance options and helps customers compare available coverage and pricing.
Related Home Insurance Guides
Explore more UAE building, contents and home insurance resources:
