Home Contents Insurance UAE: What Tenants and Homeowners Should List
A family may know roughly how much their apartment or villa is worth, but have you ever tried to calculate the cost of replacing everything inside it? Furniture, clothes, electronics, kitchen equipment, children's belongings and valuables can add up quickly.
Home contents insurance UAE can help protect eligible household possessions against insured events, subject to the policy's sum insured, limits, deductibles, conditions and exclusions.
Before buying cover, it is important to understand three different areas:
Buildings: The physical structure and eligible fixed elements of a property.
Contents: Household items and possessions kept at the insured home.
Personal belongings: Items that may be separately insured, particularly possessions taken outside the home.
The exact definitions depend on the policy. Current UAE products from insurers and insurance distributors demonstrate that contents and personal belongings can be treated differently.
What Is Home Contents Insurance in the UAE?
Home contents insurance is designed to cover eligible household possessions against specified insured events, subject to the policy wording.
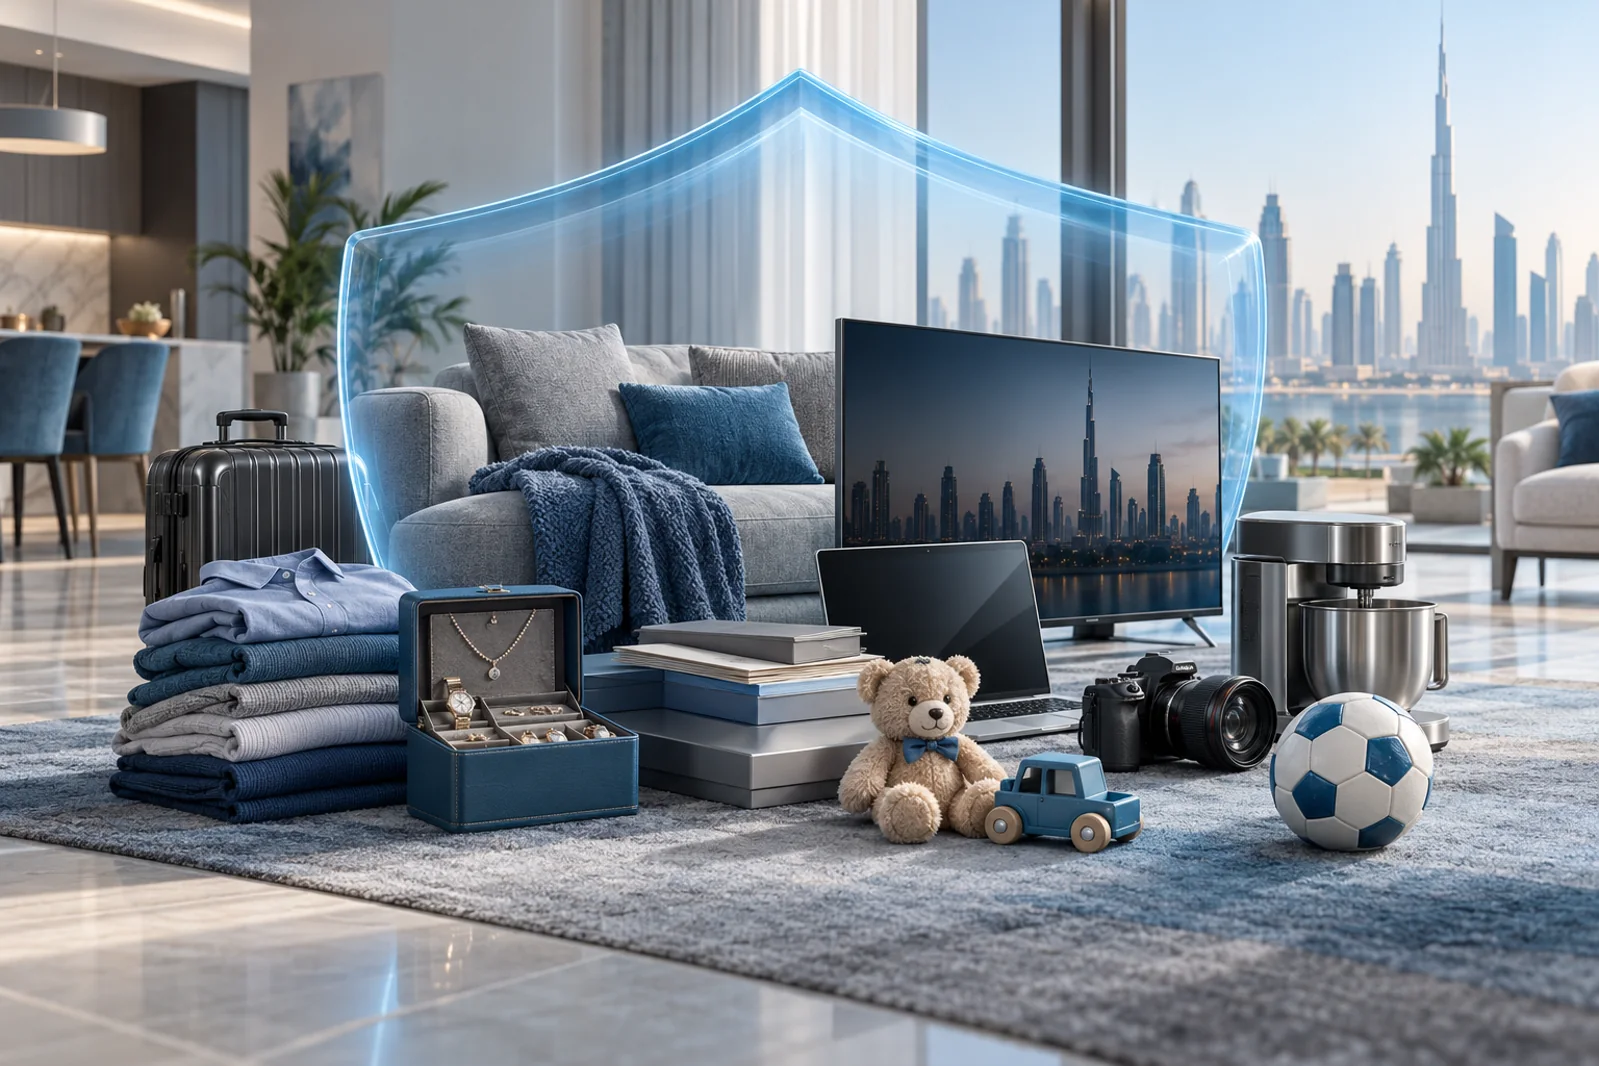
Depending on the policy, contents can include:
- Furniture
- Televisions
- Computers and electronics
- Home appliances
- Clothing
- Kitchen equipment
- Household furnishings
- Personal effects
- Sports equipment
- Children's belongings
Content insurance is different from buildings insurance. A buildings policy generally relates to the physical property, while contents cover focuses on possessions.
Some products also provide additional benefits such as alternative accommodation, liability, temporary removal of contents or household removals. These benefits are policy-specific.
Do Tenants Need Home Contents Insurance in the UAE?
Tenants can purchase contents insurance for belongings they own or are responsible for, subject to the policy terms.
A tenant generally does not insure the building itself because the tenant does not own the structure. Current UAE products explicitly demonstrate this distinction.
Tenants should check whether their policy also includes:
- Contents cover
- Personal belongings cover
- Tenant liability
- Cover for damage to eligible landlord fixtures or property
- Alternative accommodation
- Accidental damage
- Theft
- Water damage
- Temporary removal of contents
These benefits are not automatically included in every policy.
What Should Homeowners List for Contents Insurance?
An owner-occupier may need to consider both buildings and contents, depending on the property and policy.
| Category | Examples to List |
|---|---|
| Furniture | Sofas, beds, wardrobes, dining tables |
| Electronics | TVs, computers, monitors, gaming equipment |
| Appliances | Refrigerators, washing machines, coffee machines |
| Kitchen contents | Cookware, utensils, small appliances |
| Clothing | Clothes, shoes, accessories |
| Home decor | Rugs, curtains, lamps, ornaments |
| Children's items | Toys, desks, electronics |
| Sports equipment | Bicycles, fitness equipment, sporting gear |
| Household equipment | Vacuum cleaners, tools and equipment |
| Valuables | Jewellery, watches, artwork and collectibles |
The exact treatment of valuables, fixtures and appliances varies between policies, so check the policy wording before assuming an item belongs under contents.
What Should You List Room by Room?
A room-by-room inventory is one of the simplest ways to avoid overlooking possessions.
Living Room
List your sofa, chairs, coffee table, TV, sound system, gaming consoles, rugs, curtains, lamps, decorative items and books.
Bedroom
Consider beds, mattresses, wardrobes, clothing, shoes, bags, watches and personal electronics.
Kitchen
Record refrigerators, microwaves, ovens where treated as contents, coffee machines, blenders, cookware, kitchen appliances, cutlery and dinnerware.
Built-in appliances and fixtures can be treated differently from movable contents, so check the policy.
Home Office
Include laptops, desktop computers, monitors, printers, office furniture, cameras, external drives and other work equipment.
Business-owned equipment may have different insurance requirements, so do not automatically assume it has ordinary household contents cover.
Children's Room
List beds, furniture, toys, gaming devices, tablets, computers, books, bicycles and sports equipment.
Storage Areas
Do not forget tools, suitcases, seasonal clothing, household equipment, cleaning equipment and stored electronics.
Should You List Jewellery, Watches and Other Valuables Separately?
High-value items deserve particular attention because a policy may have single-item limits, category limits or specified-item requirements. Potential high-value items include:
- Jewellery
- Luxury watches
- Artwork
- Collectibles
- Designer items
- Musical instruments
- High-end electronics
- Specialist equipment
Depending on the insurer and policy, you may be asked for purchase invoices, receipts, valuation certificates, photographs, serial numbers or other proof of ownership and value.
Contents vs Personal Belongings: What Is the Difference?
| Feature | Contents | Personal Belongings |
|---|---|---|
| Main location | Usually inside the insured home | May travel with you |
| Furniture | Usually relevant | Usually not |
| TV | Usually relevant | Usually not |
| Laptop | Policy-dependent | Often relevant |
| Jewellery | May have special limits | Often separately covered |
| Watch | May have special limits | Often separately covered |
| Clothing | Usually relevant | May also be covered |
| Outside-home protection | Policy-dependent | Often the purpose of this cover |
| Worldwide cover | Not necessarily | May be available under specific cover |
How Much Home Contents Insurance Do You Need?
The contents sum insured should realistically reflect the value of eligible belongings you want to protect.
Use this process:
- Walk through every room.
- Record major items.
- Estimate current replacement costs.
- Add smaller household possessions.
- Identify expensive items separately.
- Check single-item and category limits.
- Review your inventory annually.
- Update it after major purchases.
Do not automatically use the original purchase price. Check the valuation basis stated in your policy. Some policies may use replacement cost, while others may apply depreciation or another settlement method.
Also check the wording for underinsurance, average clauses, deductibles and the applicable sum insured.
Should You Include Clothes, Shoes and Household Items?
Yes. A content inventory should not focus only on expensive electronics.
Clothing, shoes, bags, kitchenware, linen, towels, curtains, rugs, toys, books, Home decor and small appliances can collectively represent a significant portion of a household's possessions.
For example, replacing an entire wardrobe or kitchen may involve many individual items that are easy to overlook when estimating a total.
What About Electronics and Work-From-Home Equipment?
Electronics can form a substantial part of a household inventory.
Consider listing:
- Laptops
- Desktop computers
- Monitors
- Tablets
- Smartphones
- TVs
- Cameras
- Gaming consoles
- Speakers
- Smart-home equipment
- Printers
Personal electronics may have specific limits. Items regularly taken outside the home may need personal belongings cover, while business-owned equipment may require separate insurance arrangements.
Keep serial numbers and purchase records where available.
What Documents Should You Keep for Your Contents Inventory?
Useful records can include:
- Purchase invoices
- Receipts
- Valuation certificates
- Photos
- Videos
- Serial numbers
- Warranty documents
- Bank or card purchase records
- Ownership documents for specialist valuables
These records can help establish ownership and value if you make a claim. However, do not assume that every insurer requires every document.
What Happens If You Underestimate Your Contents Value?
Suppose you insure your contents for AED 100,000, but the eligible belongings you would need to replace are worth substantially more.
The policy may then provide less protection than you expected. The exact consequences depend on the policy's settlement provisions and whether it contains an underinsurance or average clause.
Before choosing your sum insured, check:
- Sum insured
- Underinsurance provisions
- Average clause
- Settlement basis
- Depreciation
- Deductible
- Individual item limits
Do not assume that every UAE home insurance policy applies the same settlement mechanism.
What Home Contents Insurance May Not Cover
Exclusions vary by policy. Depending on the product, they may include:
- Wear and tear
- Gradual deterioration
- Certain unoccupied-home situations
- Deliberate damage
- Unspecified high-value items above applicable limits
- Items outside the home without appropriate cover
- Business equipment
- Cash or certain financial instruments
- Certain water damage or natural events
Always read the exclusions, conditions and policy schedule before relying on a particular benefit.
What Should Tenants Check Beyond Their Contents?
Tenants should review:
- Contents sum insured
- Personal belongings
- Tenant liability
- Landlord fixtures and fittings
- Alternative accommodation
- Accidental damage
- Water damage
- Theft
- High-value items
- Temporary removal of contents
- Moving-house cover, where available
Tenant liability is worth checking because the policy may provide protection for certain legal liabilities arising from damage, subject to its terms.
What Should Homeowners Check?
Owner-occupiers may need to consider:
- Buildings: The physical property and eligible fixed elements.
- Contents: Movable household possessions.
- Personal belongings: Items taken outside the home.
- Valuables: Jewellery, watches, artwork and collectibles.
- Alternative accommodation: Where provided under the policy.
- Liability: Personal or occupier liability where included.
For landlords, buildings and loss-of-rent considerations may be more relevant than the tenant's personal contents.
Current UAE products demonstrate that occupancy status matters.
How to Create a Home Contents Inventory in 30 Minutes
- Step 1: Start with the largest rooms.
- Step 2: Record high-value items first.
- Step 3: Take photos or video of each room.
- Step 4: Record model and serial numbers for electronics.
- Step 5: Save invoices and valuation documents.
- Step 6: Estimate smaller household items using the valuation method allowed by your policy.
- Step 7: Separate items that may require specific declaration.
- Step 8: Compare your total with the proposed sum insured.
- Step 9: Review the inventory after major purchases.
If your policy requires individual declaration, do not combine those items into general categories.
Common Home Contents Insurance Mistakes in the UAE
- Insuring only the furniture
- Forgetting electronics
- Ignoring clothing and shoes
- Not declaring expensive jewellery where required
- Assuming laptops automatically have worldwide cover
- Confusing contents with buildings insurance
- Using the original purchase price without checking the valuation basis
- Setting the sum insured too low
- Failing to update the inventory after major purchases
- Assuming the landlord's insurance covers a tenant's belongings
- Ignoring tenant liability
- Not keeping proof of ownership
Home Contents Inventory Checklist
Save this checklist and use it when preparing your inventory:
- Furniture
- TVs and entertainment equipment
- Computers and laptops
- Tablets and smartphones
- Kitchen appliances
- Cookware and kitchenware
- Clothing and shoes
- Beds and mattresses
- Rugs and curtains
- Children's belongings
- Sports equipment
- Tools and household equipment
- Jewellery
- Watches
- Artwork
- Collectibles
- Cameras
- Musical instruments
- Home-office equipment
- Other high-value possessions
For each valuable item, check whether your policy requires separate declaration.
Frequently Asked Questions
Home Contents Insurance UAE: Build an Accurate Inventory Before You Buy
Creating an accurate inventory is one of the most useful steps you can take before purchasing home contents insurance UAE.
List possessions room by room, distinguish contents from buildings and personal belongings, identify high-value items, keep evidence of ownership and value, and calculate a realistic sum insured based on the valuation basis in your policy.
The objective is not simply to select the largest possible insurance amount. It is to make sure your policy accurately reflects the eligible possessions you want to protect and the terms under which those possessions would be settled.
Protect Your Home Contents in the UAE
Whether you are a tenant, owner-occupier, landlord or homeowner with valuable belongings, your insurance needs can differ.
Explore home insurance options with Insure Now and consider the contents, personal belongings, buildings and additional covers relevant to your situation.
Related Home Insurance Guides
Explore more UAE home and contents insurance resources:
